
For Texas employers with Blue Cross group health
Texas Approved Blue Cross's 19.19% Small Group Increase for 2027
The rate is final. It takes effect January 1, 2027, and it covers nearly 400,000 Texas members. Most employers won't see their number until the renewal letter arrives, and by then there is no time left to do anything about it.
Independent brokerage · Frisco, TX · Licensed in 13 states · No cost to look
Blue Cross and Blue Shield of Texas received final approval for a 19.19% average rate increase on its Texas small group health plans, effective January 1, 2027. Blue Choice PPO rises 17.59% and Blue Advantage HMO rises 24.93%. The Texas Department of Insurance approved the filing at 100% of what Blue Cross requested.
This is the second consecutive year Texas approved a Blue Cross small group increase at exactly the amount filed.
What the state approved
- 19.19%
- Average approved increase on Blue Cross Texas small group plans for 2027
- 100%
- Of what Blue Cross asked for, granted by the state, two years running
- 11.5%
- Of the increase is a morbidity surcharge driven by employers leaving the pool
- 399,954
- Texas members covered by the approved rate
This isn't an estimate. It's approved.
Blue Cross and Blue Shield of Texas asked the state for a 19.19% average increase on its Texas small group plans. The Texas Department of Insurance reviewed it and granted the request in full. The official determination: Not Unreasonable.
Blue Cross asked for more than any other carrier left in the Texas small group market, and got it:
- Blue Cross Blue Shield of Texas: 19.19%
- Scott and White Health Plan: 18.35%
- UnitedHealthcare Insurance Company: 16.44%
- UnitedHealthcare of Texas: 16.05%
- Baylor Scott & White Insurance Company: 14.34%
Every one of those was approved at exactly the amount the carrier requested. If you were waiting for the state to push back, it already didn't, twice. Blue Cross's 2026 small group increase was approved the same way, at 100% of request, on every product.
| 2026 (approved) | 2027 (approved) | Two years combined | |
|---|---|---|---|
| Blue Choice PPO | 15.80% | 17.59% | +36.2% |
| Blue Advantage HMO | 15.18% | 24.93% | +43.9% |
| All plans (average) | 15.68% | 19.19% | +37.9% |
Scroll the table horizontally on narrow screens.
Your renewal can land above 19%
The approved number is a market average. Three things get added on top of it before your renewal is calculated.
Your team got a year older. Small group plans price every employee by single year of age, from 21 to 63. Everyone has a birthday before renewal. That cost is automatic.
Where you are and what you picked. Your rating area and your plan choice both move the price.
When you renew. Blue Cross raises the base rate 1.78% every quarter through 2027. A business renewing in October pays about 5.4% more than a business renewing in January, same plan, same coverage, different month.
That is how an approved 19% becomes a 22% or 25% renewal letter. Across all Blue Cross small group plans, the approved range runs from 9.3% to 42.4%.
You're paying for the employers who left
This is the part worth understanding, because it explains why next year won't be better.
In its filing, Blue Cross adds an 11.5% population morbidity adjustment. In plain English, morbidity means how sick the covered group is.
Blue Cross's own explanation: healthier companies have been leaving the small group pool for self-funded and level-funded plans. The businesses left behind are, on average, more expensive to cover. So the price goes up for everyone who stayed.
Read that again. The carrier is saying, in a filing signed by its actuary and approved by the state, that part of your increase exists because other employers found a better option and took it.
Every year you stay, the pool gets smaller and more expensive. This is not a one-time correction. It is a cycle, and it is already running.
37% of covered workers at companies with 10 to 199 employees are already on a level-funded plan. The migration Blue Cross describes in its filing is not theoretical. It is most of the market.
And no, this isn't a carrier padding its margin. Blue Cross paid out 89 cents of every premium dollar in claims on this block last year. Its parent company lost $1.9 billion in 2025. That is a carrier repricing to survive, which is exactly why it doesn't stop. The lever you control is not their margin. It's how your plan is funded.
Four moves, and three of them don't disrupt your team
Market the renewal properly
Most employers never see a competing quote. Blue Cross holds about 70% of the Texas commercial market, and a broker who only sells Blue has no reason to shop it. We take your renewal to multiple carriers and show you every number side by side.
Look at level funding
A level-funded plan lets a healthier-than-average company pay a steady monthly amount and get money back at year end if the team stays healthy. You're priced on your own group instead of the shared pool, the pool Blue Cross says is getting more expensive. Stop-loss insurance caps your downside.
Consider ICHRA or QSEHRA
Instead of buying a group plan, you give each employee a set tax-free dollar amount to buy their own coverage. Your unpredictable renewal becomes a fixed budget line you control.
Adjust the plan design
Prescription drug carve-outs, spousal provisions, and tiered network options can bend the cost without gutting the benefit your team actually uses.
You don't have to change carriers, plans, or your renewal date to get a second opinion. A broker-of-record letter just moves who services your plan. Your coverage doesn't change at all. And the commission is already built into your premium whether your current broker is working for it or not.
Who's reading your renewal
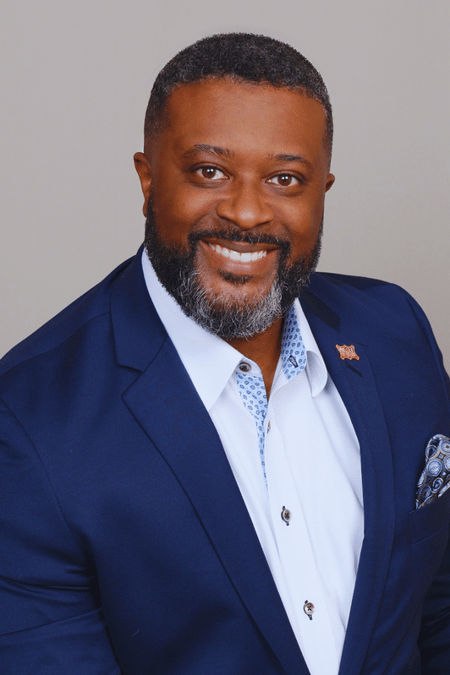
Deon R. Williams, M.Jurs, CLCS, AIC, AINS, founded 4J Insurance Brokerage in Frisco. He spent years as a claims adjuster and an SIU investigator before moving to the brokerage side, and holds a Master of Jurisprudence in Risk Management from Texas A&M School of Law.
When Deon reviews your renewal, he's reading it the way a claims adjuster reads a policy, looking for the gaps that only show up after something goes wrong.
4J is independent. We are not captive to Blue Cross or anyone else, which is the entire reason we can tell you what your renewal actually says.
M.Jurs · CLCS · AIC · AINS · SDVOSB · HUB · MBE · Licensed in 13 states
Get your renewal reviewed before the letter arrives
Send us your current plan and renewal, and we'll tell you what's driving your number and what your options are. No cost. No obligation. If your current setup is already the best available, we'll say so.
If you renew January 1, you have about seven weeks. That's tight, but it is not too late to market the renewal. If you renew later in 2027, you have real room to work with, and starting now is how you use it.
Request My Renewal Review
Questions employers are asking
Is the 19% increase approved?
Yes. Blue Cross filed for it in June 2026, and the Texas Department of Insurance approved it in full. It is final and takes effect January 1, 2027.
Does this apply to my company?
The approval covers Texas small group ACA plans, generally employers with 50 or fewer full-time-equivalent employees. Larger groups are priced on their own claims experience and are seeing increases in the same range.
Can I switch brokers without changing my plan?
Yes. A broker-of-record letter reassigns who services your existing plan. Your carrier, coverage, network, and renewal date all stay the same.
Will changing anything disrupt my employees?
Marketing your renewal and reviewing funding options changes nothing for your team unless you decide to act. Most of what we do happens before any employee sees a difference.
How much does a renewal review cost?
Nothing. Broker commission is already built into your premium. You are paying for a broker either way.
When should I start?
About 90 days before your renewal date. Sooner is better, carriers need time to quote, and rushed renewals default to whatever the incumbent offers.
Your renewal is already written. Your response isn't.
Call (817) 750-0421 or use the form above.
2591 Dallas Pkwy, Suite 300, Frisco, TX 75034
Rate information reflects filings submitted by Blue Cross and Blue Shield of Texas to the Texas Department of Insurance and published by CMS at ratereview.healthcare.gov. 2026 and 2027 figures are final approved rates; the 2027 determination was issued as “Not Unreasonable.” 4J Insurance Brokerage is an independent brokerage and is not affiliated with, endorsed by, or acting on behalf of Blue Cross and Blue Shield of Texas or Health Care Service Corporation. Plan availability, pricing, and suitability vary by group. This page is general information, not a quote or a recommendation for any specific employer.
Have 50 to 500 employees, or want to see every option? Read Blue Cross renewal alternatives for Texas employers.
Rather just talk it through?
No cost, no obligation. If your current setup is already the best available, we'll tell you.